Some links on this page are affiliate links. If you book or buy through them, we may earn a small commission at no extra cost to you. It never changes what we recommend — every price here is one we would pay ourselves.
A kiosk charging 5% costs $25 in fees and rate spread. The same $500 pulled from an ATM and spent on a no-fee card costs whatever the local bank charges, which is usually a flat fee rather than a percentage.
What the Machine Takes
An ATM is a vending machine for cash, and like any vending machine it takes a cut. Airport currency kiosks take a bigger one. The spread between the two is the whole story.
Exchanging cash at an airport kiosk typically costs 5 to 10% in fees and unfavorable rates. A no-foreign-transaction-fee credit card eliminates exchange fees. That is the recommended approach for managing trip costs on the ground in Europe. Cards named for this purpose include Charles Schwab, Capital One Venture and Chase Sapphire. Those are the cards people actually report using, not a ranking.
Here is the practical split. Pay by debit card as you travel, but take cash out of an ATM so you always have some on hand for street food and other smaller, cheaper items. That is the pattern that shows up again and again in trip reports. Big purchases go on the card. Small ones go in coins and notes. The ATM visit is a top-up, not a funding strategy.
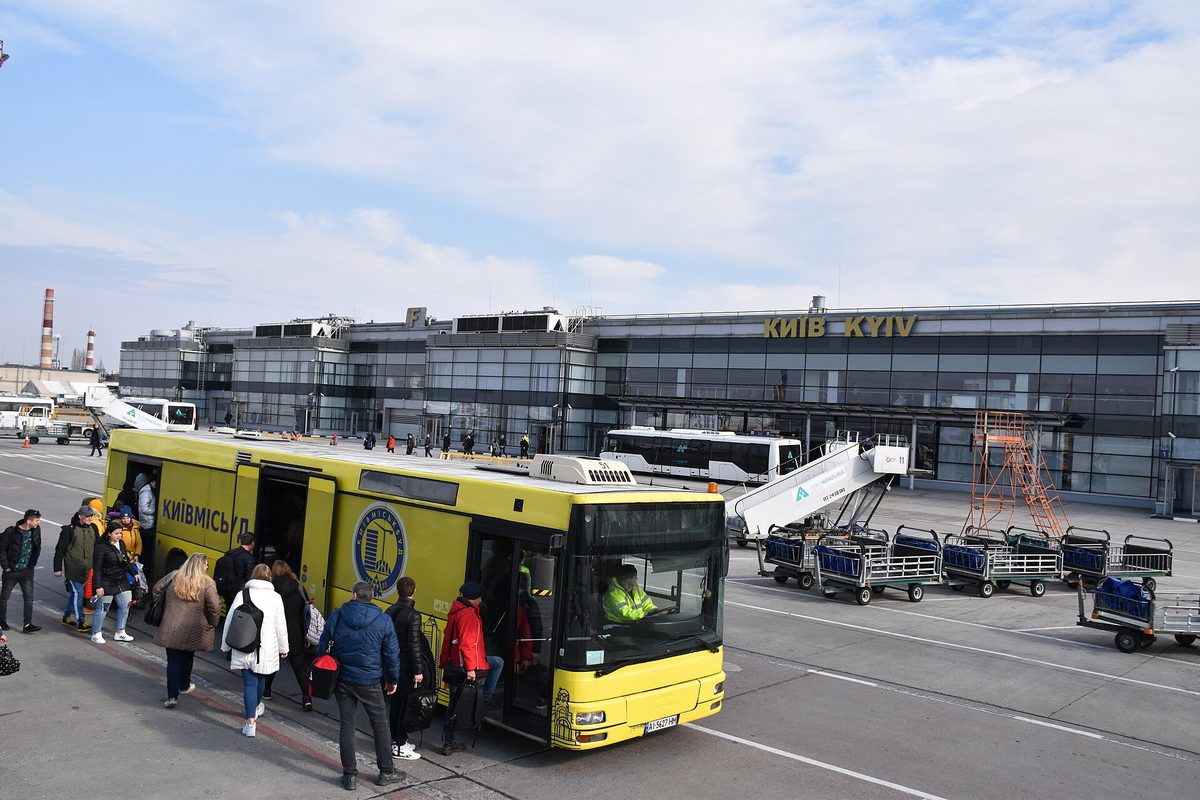
The mechanics at the machine matter more than people expect. Most airport arrivals halls put the currency kiosks directly in the path from baggage claim to the exit, brightly lit and staffed, while the ATMs sit off to the side near the toilets or the car rental desks. That placement is not an accident. The kiosk is the first thing a tired traveler sees and the last thing they want to comparison shop. Walking past it costs nothing and takes about ninety seconds.
When the ATM does come up, it will usually ask whether to charge the withdrawal in the local currency or in dollars. Always pick the local currency. Choosing dollars hands the conversion to the machine’s own bank at a marked-up rate, which is the same trick the kiosk pulls, just with a different logo on the screen. The machine may also offer a “guaranteed rate” — declining it is almost always cheaper, because the guarantee is priced in. And the withdrawal itself is not instant: the machine whirs, counts, and dispenses, and on a bad day it prints a receipt and no cash. If that happens, keep the receipt, because the amount is usually reversed within a few business days, but the reversal is far easier to argue with paperwork in hand.
Card networks occasionally flag a first foreign withdrawal as suspicious and freeze the transaction. A quick call or app confirmation clears it, but it is worth telling the bank the travel dates before leaving home so the first attempt at the airport does not get declined in front of a queue. Some travelers carry a second card from a different bank for exactly this reason, kept in a separate bag from the first.
The 5 to 10 Percent
Run the numbers on a $500 withdrawal. A kiosk charging 5% costs $25 in fees and rate spread. At 10%, it costs $50. That is a night in a hostel, or two, depending on the city. The same $500 pulled from an ATM and spent on a no-fee card costs whatever the local bank charges, which is usually a flat fee rather than a percentage. Flat fees punish small withdrawals. Percentage fees punish large ones. The kiosk is the percentage version.
That distinction shapes how the money should come out. A flat fee of a couple of dollars is trivial on a large withdrawal and annoying on a small one, so the sensible move is to take out a meaningful amount less often rather than a small amount at every machine. The counterargument is carrying a lot of cash, which is its own risk. Most people settle somewhere in the middle: enough for several days of small purchases, not so much that losing a wallet ruins the trip. Splitting cash between a money belt and a day bag is the standard habit, and it costs nothing to adopt.
Some accounts support 40 or more currencies for holding and exchange, and come with linked low-cost debit cards. That structure makes it easier to avoid international fees when spending overseas. It is a real option and it is not free. You still pay for the conversion somewhere in the chain.
What the Cash Is Actually For
Small, cheap items. That is the category. Street food, tips, entrance fees tacked onto a tour, a bottle of water. Tours in some regions run 4 to 8 hours with several stops, and occasionally there are additional entrance fees or tips for entertainers on top of the ticket price. Cash handles that without a card machine and without a minimum spend.
Not everything costs money. Forest Service sites and many state parks charge no entrance fee at all. That is $0, and it is worth knowing before you assume every stop on a route has a gate.
Bigger organized days are where the numbers get specific. A day trip into one of the major wine regions in Georgia came to $20.40 per person, plus about $10 total in additional fees for optional wine tastings along the way. Call it $30.40 per person for the full day if you taste. That is the kind of figure that makes a trip long instead of short.
The small-cash category is also where card machines quietly fail. A market stall with a card reader that has lost signal, a rural bus where the driver wants coins, a church charging a small entry fee with a handwritten sign and a tin — these are not scams, they are just places where the infrastructure is thin. Having a few notes and a pocket of coins means the day keeps moving instead of stalling at the counter. Vendors sometimes cannot break a large note, either, so it pays to keep smaller denominations on hand rather than one big bill. Breaking a large note at a supermarket or a chain cafe early in the day is a reliable way to seed the wallet with usable change.
For the days built around one attraction, buying the ticket first keeps things simple.
The Line Items Nobody Counts
Museum fees. A drink. Whatever you choose. These are the fourth bucket in any budget, after transport, beds and food, and they are the bucket that quietly decides whether a trip runs three months or five.
One more thing about totals. Some trip dates overlap, so months get used for clarity, and for various reasons people pay for days they did not use. The result is a total greater than 365. That is normal. Budgets built on a clean 365-day year are fiction.
The same logic applies to the small stuff over a long trip. A dollar here and two there does not register on any single day, but a daily coffee, a museum entry, a beer with dinner and an occasional splurge add up to a number that dwarfs any single airport kiosk fee. The kiosk is the visible, one-time loss people fixate on. The daily drip is the invisible one, and it is the one that actually changes how long a trip lasts. Tracking it loosely, even just noting spend at the end of each day, tends to surface the leaks before they compound.
Solo, Single, Same Math
There is no gatekeeping on what solo travel should look like. If you left on your own and you are building a trip that feels right, that is the trip. The fees do not care. The ATM charges the same 5 to 10% whether one person or four are splitting the room.
The one place solo travel shifts the math is shared costs. A tour with a flat per-vehicle price, a taxi from the airport, a rented room — those split across a group and do not split alone. The wine day at $30.40 per person is per person regardless, but a car full of people going the same direction costs the same whether it holds one or four. Solo travelers absorb that difference, which is why walking, buses and joining group departures tend to show up so often in single-traveler budgets. None of it changes the currency rules. The card still does not charge for crossing a border, and the kiosk still takes its cut.
So the sequence is simple. Land. Do not change money at the airport kiosk. Withdraw a modest amount, keep it for the small stuff, and put everything else on a card that does not charge you for crossing a border. Then go spend the $30.40 on the wine day, because that is what the money was for.
Leave a Reply